Index funds for UK beginners
A plain-English look at tracker funds: diversification, fees, time horizon and the real risk of loss — without stock-picking hype.
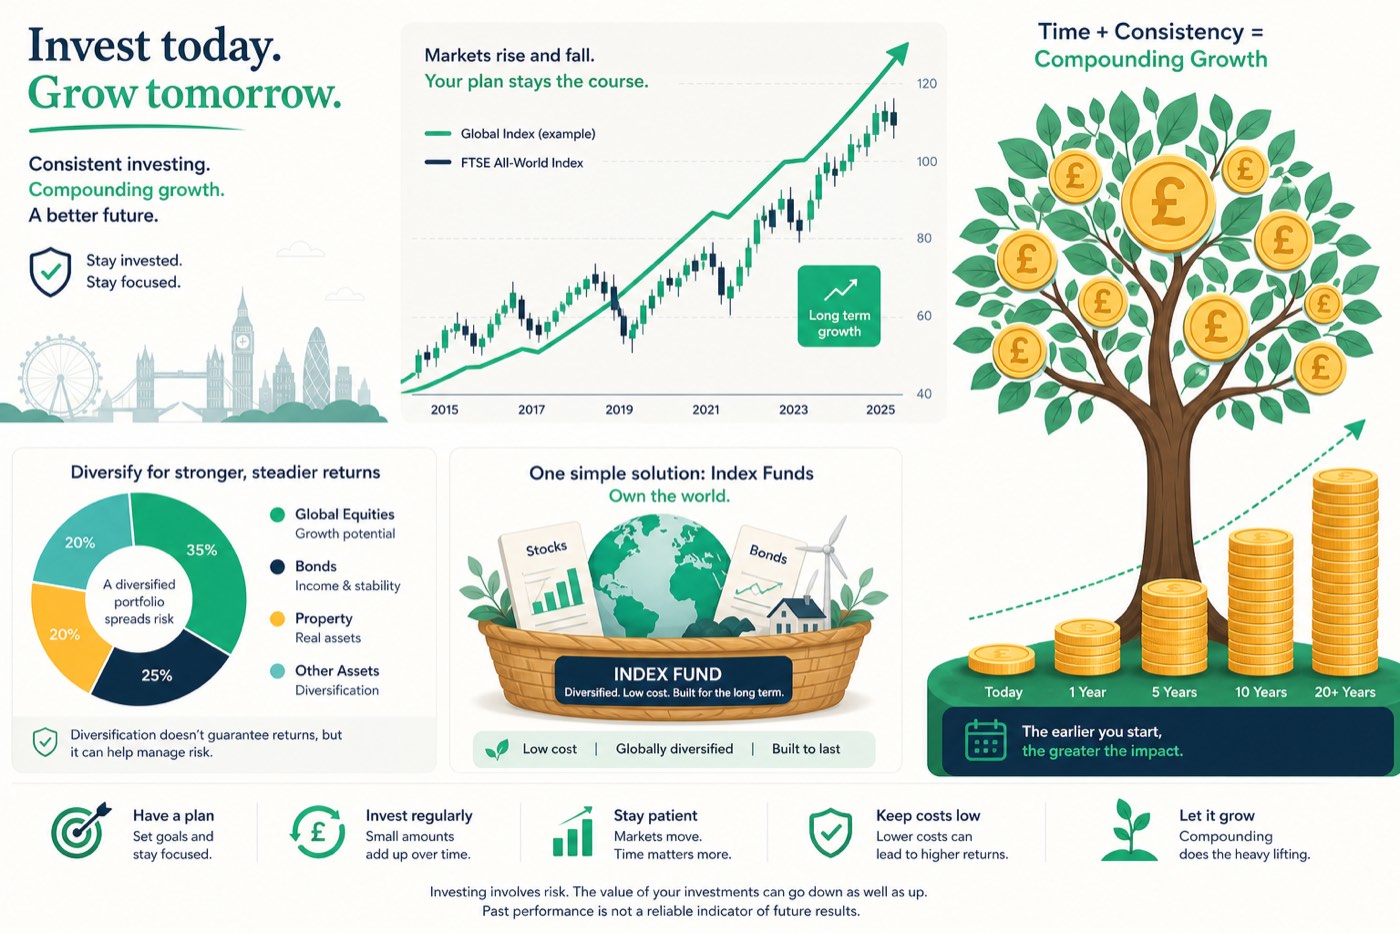
An index fund (often called a tracker) aims to follow a market index such as global shares rather than beat it with clever stock picks. For many long-term UK investors, that simple idea — paired with low fees and a sensible wrapper like a Stocks & Shares ISA — is enough. Nothing here is personal advice, and you can get back less than you invest. Past performance is not a reliable guide to future results. Only consider investing money you will not need for several years, ideally five or more, after debts and an emergency fund are under control.
Who this guide is for
UK beginners exploring diversified index funds for money they can leave invested for at least five years and whose emergency cash is already secure.
Not for: Anyone needing guaranteed returns, short-term deposit money or a personalised fund recommendation; investments can fall substantially.
What an index fund is trying to do
Instead of paying a manager to choose "winning" companies, a tracker holds a wide slice of the index it follows. A global equity index fund may own thousands of companies across countries. That spreads single-company risk, though it does not remove market risk: when markets fall, trackers fall too.
Funds can be structured as OEICs, unit trusts or ETFs. The label matters less for beginners than ongoing charges, tracking quality, and whether you understand the index (global shares vs a narrow sector fad).
Accumulation units automatically reinvest income inside the fund; income units pay dividends out. Neither choice removes market risk. Currency moves also matter for global funds priced in sterling — a strong pound can dampen overseas returns in a given year even if foreign markets rise. That is normal, not a sign the tracker is "broken".
Costs quietly decide long-term outcomes
A 1% annual fee versus 0.2% sounds small until compounding runs for decades. Platform fees, fund ongoing charges and trading spreads all add up. Compare the total cost of ownership, not a single teaser rate. Cheap is not automatically best if the fund is extremely narrow or hard to understand — but for broad global trackers, low cost is usually a feature, not a bug.
Read the key investor information document. If you cannot explain what you own in one sentence, pause.
Be wary of funds that hug an index most of the year then take big active bets — you may pay active prices for muddled behaviour. Synthetic or leveraged products are a different animal again and are rarely suitable for cautious long-term beginners. If marketing leans on excitement rather than clarity, walk away.
Risk, time horizon and behaviour
Equity index funds can drop 20% or more in nasty years and take time to recover. If you might need the money for a house deposit next year, cash savings are usually more appropriate than shares. Volatility is the price of admission for long-term equity growth — it is not a temporary glitch.
- Clear expensive consumer debt before investing spare cash
- Build an emergency fund in accessible savings
- Invest only money earmarked for long-term goals
- Avoid panic-selling after headlines
Rebalancing is another behaviour test. If you add bonds or cash later to reduce swings, do it to a written plan — not because a TV guest sounded alarmed on a Tuesday. This is educational content, not a recommendation to buy any fund or use any platform.
How beginners usually access trackers in the UK
Most people buy via an investment platform or app inside a Stocks & Shares ISA (annual allowance £20,000 for 2026/27 across ISA types you use) or a pension. Workplace pensions often already include tracker options — check charges there before opening five new accounts.
For regulated guidance frameworks and scam warnings, use MoneyHelper and the FCA. Never invest based on a tip from an unverified social account.
A practical beginner path many UK adults consider — after emergency savings — is a low-cost global equity tracker inside a Stocks & Shares ISA, funded monthly. That sentence is a description of a common approach, not a personal recommendation. Your risk tolerance, age, debt and goals may point elsewhere, including simply holding more cash for longer.
What the index actually owns
An index fund follows a stated index using rules rather than a manager selecting securities. “Passive” does not mean low risk or fully diversified. A FTSE 100 fund owns large UK-listed companies and can be concentrated by sector; a global all-cap fund spreads exposure more widely but still carries equity, currency and market risk.
| Feature | Fund X | Fund Y |
|---|---|---|
| Index | FTSE 100 | Global all-cap index |
| Ongoing charge | 0.07% | 0.23% |
| Illustrative cost on £10,000 | £7/year | £23/year |
| Diversification | Large UK-listed firms | Thousands globally |
Costs shown are illustrations and exclude platform fees, dealing charges and tracking difference. The cheaper fund is not automatically better if its exposure does not fit the plan. Tracking difference—the gap between fund return and index after costs and implementation—is more informative than headline fee alone.
Second example: Ellie invests £200 monthly. Her platform charges 0.25% yearly and the fund 0.20%, roughly 0.45% before transaction effects. After a market fall her £4,800 of contributions may be worth £4,050. Selling because the one-year return is negative converts a normal equity risk into a permanent loss. She had chosen a ten-year horizon and kept emergency cash separate, so she reviews the index and costs rather than reacting to headlines.
- Define goal, earliest withdrawal date and maximum tolerable fall.
- Choose asset class before choosing a fund; shares and bonds perform different jobs.
- Read the index methodology, geographic/sector concentration and whether income accumulates or distributes.
- Add fund, platform, dealing and foreign-exchange costs.
- Use an FCA-authorised platform and understand FSCS limits; protection does not cover market losses.
- Review annually, not hourly, and rebalance only to a written allocation.
Replication can be physical or synthetic; either needs reading rather than a blanket judgement. Accumulation units reinvest income inside the fund, while income units distribute it. Outside an ISA, accumulation does not make distributions irrelevant for tax records. A Stocks & Shares ISA can shelter eligible holdings within the £20,000 2026/27 allowance.
Check the fund's current key investor document and register entries. Confirm that its benchmark has not changed since your original selection. Diversification cannot prevent loss, and past performance is not a reliable forecast. This is general education, not regulated investment advice.
Worked UK example: fee drag on a long-term pot
Morgan invests £250 a month into a global equity index fund for 25 years. Ignoring markets' ups and downs for a moment and using a simplified 5% average annual return before charges: at a 0.2% annual charge the pot grows more than at a 1.0% charge by tens of thousands of pounds over that horizon in typical fee-drag illustrations. Real markets will not return a smooth 5% — some years will be sharply negative — which is exactly why Morgan only invests money that can stay invested. Hypothetical maths for education, not a forecast or advice.
Step-by-step checklist
- Confirm emergency savings and high-interest debts are handled first
- Decide a time horizon of at least five years
- Learn what index the fund tracks in one plain sentence
- Compare ongoing charges and platform fees
- Consider using the £20,000 ISA allowance (2026/27) if appropriate
- Set up a regular contribution you can sustain
- Write down rules for not panic-selling in a downturn
Common mistakes
- Treating a tracker as 'safe' because it is diversified
- Chasing last year's hottest sector index
- Ignoring fees because the amounts look small
- Investing money needed for near-term spending
When to get regulated help
Read impartial guidance on MoneyHelper and check firms on the FCA Register. For tax wrapper rules see GOV.UK. Smart Money Answers does not provide regulated investment advice.
Frequently asked questions
Can I lose money in an index fund?
Yes. Diversification reduces single-company risk but not market risk. Values fall as well as rise.
Are ETFs better than index funds?
Both can track indexes. Choose based on costs, access on your platform and whether you understand the product — not on marketing labels.
How much do I need to start?
Many platforms accept small regular amounts. Consistency and time in the market usually matter more than a large first lump sum.
Is this personal advice?
No. This is general information only. Consider speaking to an FCA-regulated adviser if you need a personal recommendation.